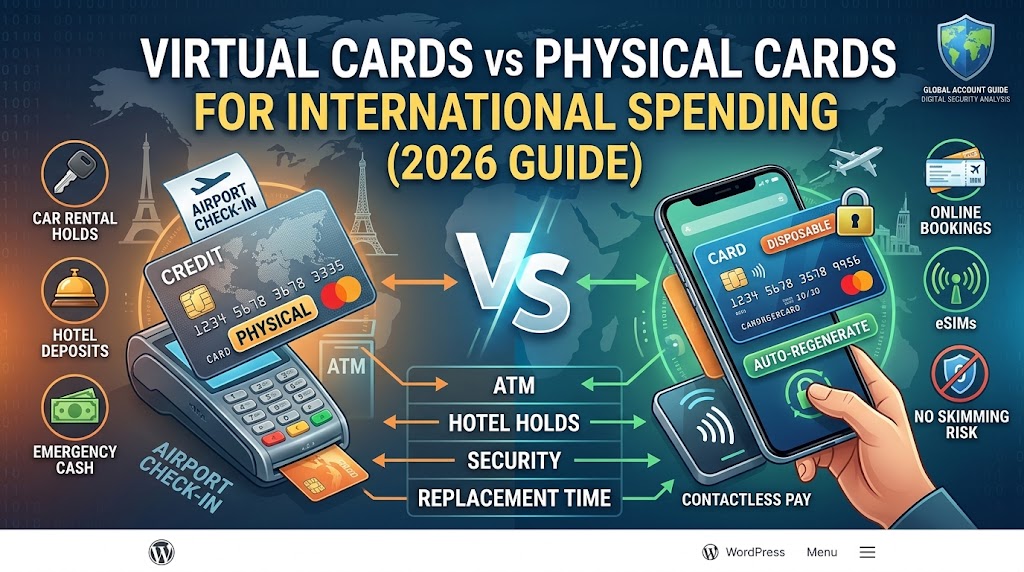
Plan travel payments around the tasks you actually need: booking, a hotel or rental deposit, transport and cash. This guide compares card limitations and includes a trip worksheet for arranging payment methods that do not all depend on one phone or account.
Editorial & Travel Advisory Notice: Global Account Guide delivers independent payment system reviews and digital security analysis. Card issuance rules, tokenization compatibility, and offline EMV terminal policies depend on your issuing institution. Review our Financial Disclaimer for regulatory disclosures.
Core Architectural Differences: Physical vs Virtual Cards
While both form factors draw from your underlying account balance, their underlying payment infrastructure functions differently in international transaction environments:
- Physical Payment Cards: Built with contact EMV chips, magnetic stripes, and static card details (Primary Account Number, expiration date, and CVV). They support offline cryptographic PIN verification when data networks are unavailable and interface with global ATM mechanisms.
- Multi-Use Virtual Cards: Software-generated 16-digit credentials stored inside digital wallets (Apple Pay, Google Wallet) or web applications. They allow custom balance caps and instant app-based locking without affecting other cards.
- Single-use virtual cards: These replace card details under the issuer’s rules and differ from a reusable wallet card. Revolut excludes its single-use card from subscriptions, hotel or car-rental deposits, cash withdrawals and Apple Pay or Google Pay. Check the required payment type before booking.
Comparison Matrix: Virtual Cards vs Physical Cards Travel Framework
The table below summarizes operational capabilities, acceptance rates, and security parameters across different card types for international spending:
| Travel task | Confirm before relying on it | Backup to arrange |
|---|---|---|
| Cash withdrawal | Issuer permission, ATM network, card or wallet support and charges. | A working physical card and another payment source. |
| Hotel or car-rental deposit | Card type, named holder, deposit amount and pickup rules. | An accepted card with enough available balance or credit. |
| Online booking | Whether later charges or card presentation are required. | A reusable card if disposable details are unsuitable. |
| Public transport | Accepted payment devices, ticket validation and fare rules. | The operator’s alternative ticket or payment method. |
| Phone loss | How account access and wallet recovery work. | A payment method independent of that phone. |
When You MUST Carry Physical Cards Abroad
1. Vehicle Rentals and Security Deposits
Before booking accommodation or a rental vehicle, ask the actual merchant which credit, debit, virtual or wallet payments it accepts for both payment and the deposit. Confirm the named holder, available funds and presentation requirements. Do not assume one rule or technical explanation covers every merchant.
2. Legacy Point-of-Sale Terminals and Unattended Kiosks
In many rural regions, toll roads, train ticket kiosks, and regional gas stations, terminals lack contactless NFC sensors. They require an EMV chip insertion or magnetic stripe swipe to authorize transactions.
3. Cash-Dominant Economies and Emergency ATM Access
ATM access depends on the issuer, network and machine. Carry a physical card when the intended withdrawal route requires one, and check withdrawal and operator charges. A network logo or an advertised fee policy does not ensure acceptance or sufficient available funds.
When Virtual & Disposable Cards Are the Superior Choice
1. High-Risk Online Travel Reservations
A disposable card can reduce reuse of exposed credentials where supported, but check whether the booking involves a deposit, delayed charge or card presentation. For example, Revolut lists exclusions for its single-use cards. No card format makes an unfamiliar merchant safe.
2. Contactless In-Person Spending in Tourist Hotspots
A mobile wallet can reduce the need to expose card details, but phone loss, account takeover and merchant fraud remain possible. Protect account access, enable supported security controls and retain a payment method independent of your phone.
3. Digital Nomad Subscriptions and Regional eSIMs
Virtual card limits can help control spending on services such as an eSIM or coworking subscription. Blocking a payment or changing a card number does not cancel a contract. Follow the merchant’s cancellation process, save confirmation and check any outstanding obligation.
The 3-Tier Security Setup for International Travelers
To maximize financial safety without risking account lockouts abroad, implement this three-tier architecture:
- The Vault Account: Your primary bank account holding the bulk of your capital, unconnected to any active physical debit card in your wallet.
- Daily Contactless Digital Layer: A multi-currency virtual card connected to your mobile wallet, loaded only with daily operating funds and protected by biometrics.
- The Emergency Hardware Backup: A dedicated physical travel debit card with zero foreign transaction fees kept securely in your luggage safe to handle deposit authorizations and cash withdrawals.
Regulatory Standards and Chargeback Rights
Fraud protections depend on the issuing country, card type, transaction and timely reporting. Network policies have exceptions, and a chargeback is not an automatic refund. Contact the issuer promptly and preserve evidence. See Visa’s policy information and exclusions.
A travel payment plan with independent backups
Illustrative trip: an online hotel booking, a rental-car pickup and a cash expense require three separate acceptance checks. A successful booking payment does not establish that the same card is accepted for the deposit at arrival.
| Trip stage | Resolve before departure | Failure to plan for |
|---|---|---|
| Online booking | Immediate payment, later charge, deposit and card-presentation rules | A disposable number is unsuitable for a later charge |
| Pickup or check-in | Named holder, accepted card type, deposit and available funds | The accepted booking method differs from the deposit method |
| Cash expense | Actual card/ATM compatibility, withdrawal limit and charges | Phone-only payment cannot obtain the required cash |
| Lost phone | Recovery route and a payment source outside that device | The wallet and account-recovery method disappear together |
Keep a merchant’s confirmation and the reservation reference. Arrange backups that do not all depend on the same phone, login or account. Test access before departure and know how to contact the issuer securely. This worksheet is about continuity of access, not a claim that any card eliminates fraud.
Frequently Asked Questions
Can I get a refund on a disposable virtual card that has already expired?
A refund may still be possible after a virtual card expires or is deleted, but handling and timing depend on the issuer and merchant. Check the issuer’s instructions, keep the transaction reference and contact support if the refund does not appear. Do not assume a universal three-to-five-day deadline.
Do virtual cards cost more in foreign exchange fees than physical cards?
No. Foreign exchange rates and transaction markups are determined by the issuing financial institution’s rate policy, not the card’s physical or digital form factor.
Can I use virtual cards for public transit systems abroad?
Check the exact transport operator’s accepted cards and devices. If the system requires tapping in and out, follow its instructions about using the same card or device. Do not assume every city accepts foreign contactless cards or every mobile wallet.